 Muslim
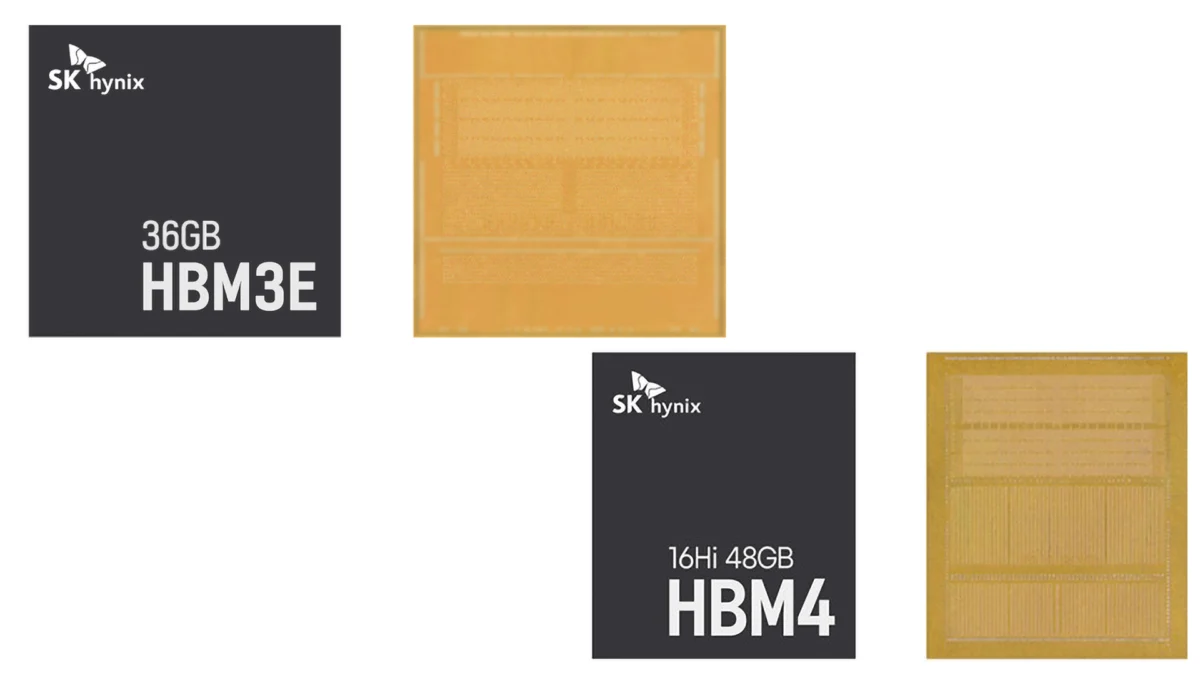
The global electronics industry is currently navigating one of its most precarious periods in recent memory. As the demand for high-performance computing, artificial intelligence, and mobile connectivity continues to surge, a persistent bottleneck has emerged: the supply of memory chips. For the titans of the industry—companies like Apple, Samsung, and Dell—the shortage is a logistical headache. For smaller smartphone and laptop manufacturers, however, it has become an existential crisis that is fundamentally altering how they design, source, and manufacture their products.
According to a recent report by Reuters, the issue has shifted from a matter of cost to one of pure availability. While price hikes are inevitably passed down to the consumer, the more pressing concern for smaller vendors is securing any supply at all. In an environment defined by scarcity, these companies are being forced to adopt extreme measures, ranging from long-term, high-risk procurement strategies to manual quality control protocols aimed at weeding out counterfeit hardware.
The Anatomy of the Shortage: Main Facts
At the heart of the current crisis is a misalignment between supply chain capacity and the rapid proliferation of memory-intensive technologies. DRAM (Dynamic Random Access Memory) and NAND flash storage are the foundational building blocks of every smartphone and laptop.
The shortage is not merely a result of factory closures or geopolitical trade disputes, though those play a part; it is a structural imbalance. As artificial intelligence models require massive amounts of memory to process data locally, and as operating systems grow in complexity, the "memory footprint" of every consumer device has expanded.
Smaller manufacturers, who lack the massive purchasing power and long-term contracts held by multinational conglomerates, are finding themselves at the back of the queue. This has led to a "survival of the fittest" dynamic in the hardware market. Companies that cannot secure memory cannot ship products, and in the fast-paced world of consumer electronics, a failure to ship is a failure to exist.
A Chronology of the Memory Crisis
To understand how we reached this point, we must look at the timeline of the supply chain volatility that has defined the 2020s.
The Pandemic Catalyst (2020–2022)
The initial tremors began during the COVID-19 pandemic. As remote work became the global norm, the demand for laptops and tablets skyrocketed, exhausting existing stockpiles. Manufacturers scrambled to ramp up production, but supply chains were brittle.
The Post-Pandemic Correction (2023–2024)
Following the initial spike, there was a period of over-correction. Many firms overestimated demand, leading to a temporary inventory glut. However, this lull proved to be a false sense of security. As companies slowed their orders, semiconductor foundries shifted focus toward high-margin chips for AI servers, inadvertently creating a supply gap for the standard DRAM and NAND modules used in consumer handsets and budget laptops.
The Scarcity Era (2025–Present)
By 2026, the shortage reached a critical juncture. The rise of "AI-ready" hardware—devices designed to run LLMs (Large Language Models) on-device—created a new baseline for memory requirements. Where 8GB of RAM was once standard, 16GB is now the minimum for competitive devices. This doubling of requirements per unit has effectively halved the available supply in the global market, leading to the current state of industry-wide desperation.
Supporting Data: The Burden of Cost and Supply
The impact of this shortage is perhaps best quantified by the "Bill of Materials" (BOM). The BOM is the comprehensive list of raw materials, assemblies, and parts required to manufacture a finished product.
Recent industry analysis indicates that memory now accounts for an staggering 60% of the total BOM for many smaller-scale devices. To put this in perspective, a few years ago, memory typically accounted for 20% to 30% of the hardware costs. When a single component consumes more than half of the total budget for a product’s physical build, the manufacturer’s margins are squeezed to the point of vanishing.
Furthermore, procurement cycles have shifted dramatically. Where manufacturers once operated on "just-in-time" (JIT) inventory management, they are now forced into "just-in-case" planning. This involves placing orders for memory modules as much as 12 to 18 months in advance. This approach ties up massive amounts of capital, creating a high-risk financial environment where a shift in consumer demand could leave a company holding millions of dollars in obsolete or unwanted memory components.
Official Responses and Tactical Shifts
In response to these pressures, manufacturers are adopting unconventional strategies to maintain their market presence.
The Fairphone Perspective
Fairphone, known for its focus on sustainable and repairable hardware, has been vocal about the difficulties of the current climate. By prioritizing longevity and modularity, the company is particularly sensitive to memory availability. For Fairphone, the challenge is not just sourcing parts, but ensuring those parts meet rigorous sustainability and performance standards. Their feedback highlights that the current market dynamics are punishing companies that refuse to compromise on quality, as they are often outbid by larger players for the highest-grade silicon.
Counterfeit Concerns
Perhaps the most alarming development is the rise of counterfeit memory. As legitimate supply channels dry up, "gray market" brokers have become more active. These entities often sell recycled, refurbished, or outright fake memory chips that are rebranded to look like premium components from major vendors like Micron, SK Hynix, or Samsung.
Smaller manufacturers are now forced to invest in secondary testing labs. Every shipment of memory chips must be subjected to stress testing and physical inspection to ensure the silicon matches its reported specifications. This adds another layer of operational cost and time, further slowing the production cycle.
Implications: The Future of Consumer Tech
The ongoing memory shortage is not merely a temporary supply chain issue; it is a catalyst for permanent change in the electronics industry.
Consolidation of the Market
The most immediate implication is market consolidation. As smaller players struggle to survive the high cost of memory and the risks of the gray market, many will likely be forced to exit the market or be acquired by larger entities. This could lead to a less diverse ecosystem, where only the largest companies have the leverage to negotiate favorable terms with memory foundries.
Design Innovation or Degradation?
Manufacturers are also re-evaluating product design. We are seeing a move toward "memory-efficient" software development and hardware designs that allow for easier upgrades. However, there is also the risk of "de-contenting," where manufacturers remove features or reduce the quality of other components—such as displays, batteries, or chassis materials—to compensate for the inflated cost of memory.
The Rise of Regional Resilience
In response to the reliance on centralized supply chains, there is a growing movement toward regionalized semiconductor production. Governments in the U.S., Europe, and parts of Asia are pouring billions into "chip sovereignty." While this will not solve the shortage in the short term, it suggests that the industry is moving away from the globalized, lean supply chains of the past toward a more distributed and redundant model.
Impact on the Consumer
For the average consumer, the implications are twofold: higher prices and a slower pace of innovation. As manufacturers struggle to manage their BOM, the price of entry-level laptops and smartphones is trending upward. Moreover, the focus on securing existing technology means that companies are less likely to experiment with cutting-edge, experimental memory standards, as they prioritize the tried-and-tested components that are currently available in bulk.
Conclusion: Navigating the Silicon Storm
The memory scarcity crisis is a stark reminder of the fragility of our modern digital infrastructure. While the tech industry is often lauded for its rapid innovation and agility, it remains tethered to the physical reality of silicon manufacturing.
For the smaller manufacturers caught in the crossfire, the coming years will be defined by strategic austerity. Success will belong to those who can master the art of supply chain resilience, who can secure long-term partnerships in an era of volatility, and who can design products that provide value even when the core components become increasingly expensive.
As we look toward 2027 and beyond, the industry is at a crossroads. Will we see a return to the surplus of the past, or is this the new normal of the "Silicon Age"? Given the insatiable hunger for memory in the era of artificial intelligence, it is highly likely that the latter is true. The squeeze on memory is not just a passing phase; it is the new gravity that will dictate the shape of the electronics industry for years to come.

 Azzam Bilal Chamdy
 Reynand Wu