 Jia Lissa
The media landscape across Asia is undergoing a profound structural metamorphosis. According to the latest "Asia Video Content Dynamics 2026" report from Media Partners Asia (MPA), the region’s video content economy is pivoting away from traditional broadcast television toward a streaming-first, IP-driven ecosystem. While demand for premium content remains at an all-time high, the industry is grappling with a widening chasm between audience engagement and financial sustainability.
The Financial Landscape: Shifting Capital in Seven Markets
The report, which examines the media environments of India, Indonesia, Korea, Malaysia, the Philippines, Thailand, and Vietnam, projects that total investment in video content across these seven markets will reach $15.1 billion by 2026. This figure marks a steady, albeit cautious, trajectory from the $14.8 billion estimated for 2025, with projections indicating a climb to $15.4 billion by 2031.
At first glance, these numbers suggest stability. However, beneath the surface, a significant "reallocation of capital" is underway. Television, once the undisputed king of media investment, currently commands approximately 60% of the total budget. Online video follows with 30%, while theatrical film accounts for 10%.
The concentration of wealth is heavily skewed: South Korea and India remain the regional titans, collectively accounting for roughly 80% of the $14.8 billion invested in 2025. Korea leads the investment pack with $6.9 billion, while India follows with $5 billion. The narrative here is not one of industry retreat, but rather a strategic migration of funds toward platforms and formats that offer higher returns and deeper audience integration.
Chronology of Change: A Turning Point for India and Beyond
The shift toward digital dominance is perhaps best illustrated by India, which reached a definitive "turning point" in 2025. For the first time, online video content investment claimed 46% of the country’s total budget, officially surpassing television’s 42% share.
The scale of consumption in India is staggering; Indian viewers logged a cumulative 420 billion hours of online video content in 2025. This explosion of digital viewership has been anchored by platforms like JioHotstar, which now commands a 58% share of premium video-on-demand (VOD) viewing in the nation, supported by a subscriber base exceeding 180 million.
The momentum in other markets is similarly distinct. In Korea, the streaming landscape is dominated by Netflix, with local powerhouse TVING maintaining a strong second-place position. In Indonesia, the local platform Vidio has emerged as a bellwether for the region’s profitability potential, having achieved EBITDA-positive status by the fourth quarter of 2025, supported by a base of over 6 million paying subscribers.
The Power of Premium Sports and Localized Film
If there is a single lever that distinguishes successful streamers from the rest of the pack, it is live sports. The MPA report highlights sports rights as the primary engine for subscriber acquisition and retention.
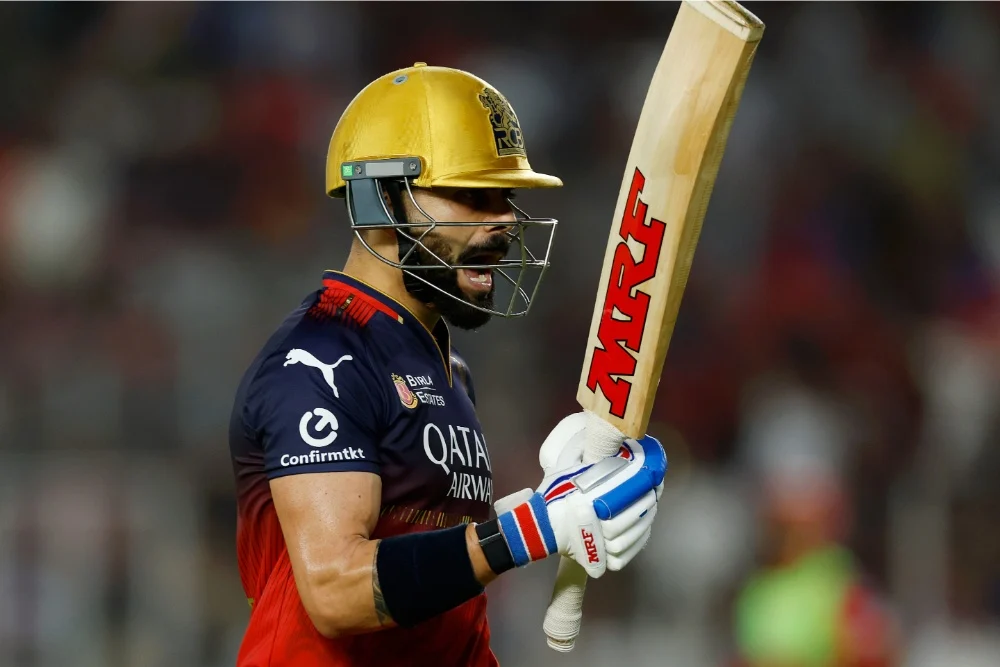
- India: Cricket remains the ultimate catalyst. During the 2026 Indian Premier League (IPL) tournament, JioHotstar saw its connected-TV reach surge by 26%, proving that live, localized sports are essential to the streaming value proposition.
- Korea: TVING utilized exclusive coverage of KBO baseball to grow its subscriber base from 5.3 million to 6.5 million. Simultaneously, Coupang Play has cemented its position by curating the most comprehensive premium sports offering in the Korean market.
- Southeast Asia: The trend holds true from Jakarta to Hanoi. In Indonesia, Vidio has integrated top-tier football—including the Champions League and Premier League—across its pricing tiers. In Vietnam, the FIFA World Cup served as a massive tailwind, driving a 22% increase in premium VOD engagement in 2025.
Beyond the digital arena, local film production has emerged as a clear growth opportunity. Audiences are increasingly rejecting imported content in favor of homegrown stories. In Vietnam, the theatrical box office grew by 20% to $213 million in 2025, with local films capturing 69% of those receipts. Indonesia saw a 10.5% increase in box office revenue to $325 million, with local titles responsible for 60% of the intake. Meanwhile, India set a new record with $1.41 billion in box office receipts, and Korea is currently experiencing a robust theatrical rebound in 2026, fueled by a stronger domestic release schedule.
Official Analysis: The Productivity Gap
Despite these successes, the "money picture" remains, in the words of MPA analysts, "less rosy." While the creative talent and the audiences exist, the conversion of this demand into healthy, sustainable profits remains elusive.
Myat Pan Phyu, an analyst at MPA, notes: "The viewership data shows demand is intact. Premium VOD engagement continues to grow across India, Korea, and Southeast Asia. This is a story of reallocation rather than retreat as capital moves toward streaming and local film, where both audiences and returns are growing."
However, the structural reality is that many long-established media firms are currently trading well below their equity book value. The era of unchecked spending is over; the firms that will survive and thrive, according to the report, are those that prioritize capital discipline, cost-trimming, and the defense of unique, proprietary IP.
Implications: Consolidation as a Survival Strategy
The report paints a bleak picture for traditional television. Advertising revenue is in a steady decline, with the Thai TV ad market, for example, dropping 18% to $422 million in 2025. Many markets are now "over-indexed" on broadcast capacity, meaning there is simply too much infrastructure chasing too little ad revenue.
Producers are also facing a "squeeze." As streamers and broadcasters become more selective, companies that rely on generic production fees are finding themselves vulnerable. The value is migrating toward "integrated studios"—entities that own their IP, have diversified revenue streams, and maintain relationships with multiple buyers. In Korea, where production costs are the highest in Asia, drama margins have been compressed to a razor-thin 5% to 10%, forcing a reckoning among local production houses.
Stephen Laslocky, vice president at MPA, offers a stark warning for industry leaders: "Asia’s video industries are not short of audiences or creative capability. They are short of structures that convert both into sustainable returns. As the margin for error narrows, management quality will become decisive."
Laslocky suggests that the future belongs to firms that can:
- Rationalize legacy costs through restructuring and the aggressive adoption of new technologies, including AI.
- Collaborate where independent investment is no longer viable.
- Protect core content that gives viewers a reason to remain loyal in a crowded market.
The Road Ahead: M&A and Corporate Restructuring
The report identifies India and Korea as the markets furthest along the path toward necessary consolidation. India’s 2024 merger of Reliance’s Viacom18 and Disney’s Star India—creating the behemoth known as JioStar—serves as the blueprint for future transactions. Korea is following suit with the proposed TVING-Wavve merger, a move intended to unlock value in a fragmented market.
Southeast Asia, while currently lagging in consolidation, is ripe for similar movements in the Philippines, Thailand, and Indonesia. Furthermore, the report highlights the potential for corporate re-engineering, specifically pointing to companies like CJ ENM, where splitting into four clearly defined business units could potentially drive equity valuations far beyond current market levels.
Ultimately, the "Asia Video Content Dynamics 2026" report serves as a wake-up call. The growth is there, the audiences are there, and the talent is there. The winners of the next decade will not necessarily be those with the largest budgets, but those who can successfully navigate the transition from legacy broadcast models to a lean, tech-enabled, and consolidated digital future. The valuation gap between the industry’s leaders and its laggards is only expected to widen.

 Siti Muinah
 Muslim