
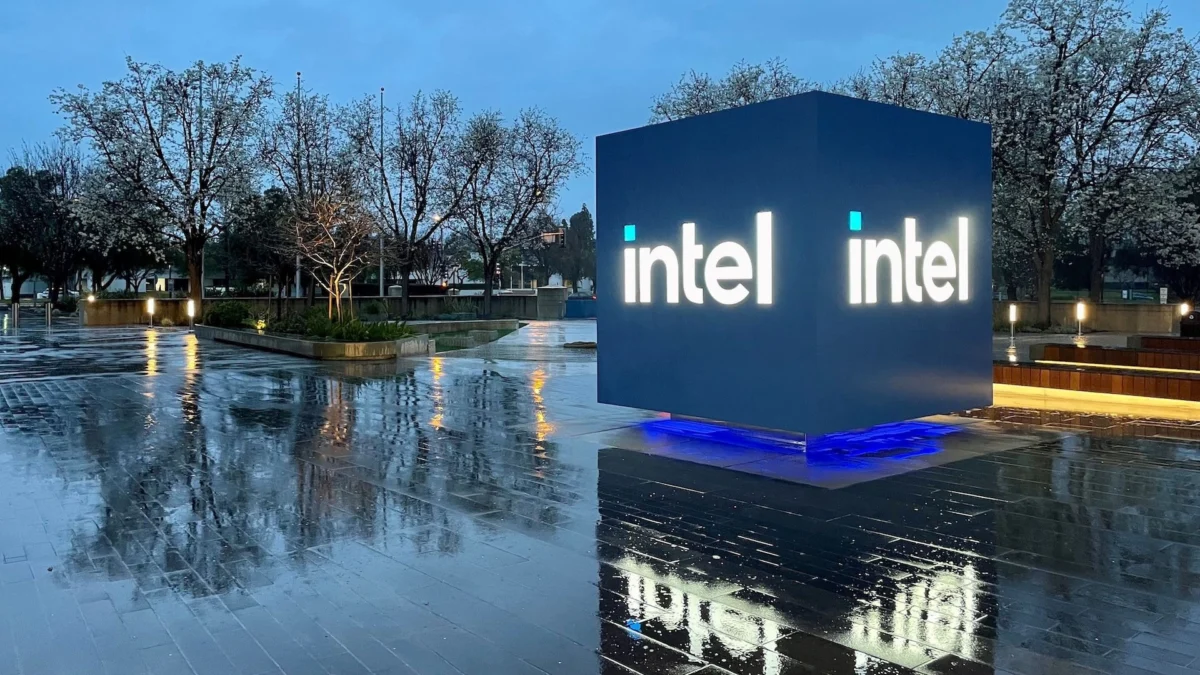
In an unprecedented collapse that has sent shockwaves through the global financial markets, Intel Corporation experienced its most harrowing trading session in history this past Friday. The semiconductor giant saw its share price plummet by 30%, a catastrophic decline that erased approximately $150 billion in market capitalization in a single day. This seismic shift—the largest single-day loss in the company’s long and storied history—has fundamentally altered the landscape of the technology sector and raised profound questions regarding the viability of Intel’s turnaround strategy in an era dominated by artificial intelligence and high-performance computing.
The fallout was not confined to Intel’s headquarters in Santa Clara. The tremor triggered a widespread sell-off across the semiconductor industry, contributing to an estimated $1 trillion in total market value evaporation across the sector. As investors scrambled to divest from chipmakers, from industry titans like NVIDIA and AMD to manufacturing powerhouses like TSMC, the event served as a sobering reminder of the interconnectedness—and the volatility—of the modern tech economy.
The Catalyst: A Financial Outlook Gone Wrong
The catalyst for this historic descent was a quarterly financial outlook that fell significantly short of Wall Street’s expectations. While market analysts had been bracing for a challenging period for the semiconductor industry, the specific guidance provided by Intel signaled deeper, structural problems within the company’s core business operations.
At the heart of the disappointment was the Client Computing Group (CCPG), long considered the bedrock of Intel’s financial health. The CCPG, which houses the company’s lucrative PC and laptop processor business, is projected to see a decline of more than 20% in sales. This anticipated downturn is particularly alarming, as the CCPG has historically functioned as Intel’s primary cash cow, funding the company’s massive capital expenditures and its ambitious attempts to regain leadership in semiconductor manufacturing.
When Intel management unveiled these figures, the market reacted with immediate and aggressive pessimism. Investors, who had been pinning their hopes on a recovery led by the company’s "IDM 2.0" strategy, suddenly found themselves confronted with the prospect of declining revenue in the very segment that was supposed to provide stability.
Chronology of a Collapse: Friday’s Downward Spiral
The trading session on Friday can be categorized as a cascade of negative momentum. The chronology of the event paints a picture of a market losing faith in real-time.
- Pre-Market Trading: As Intel released its financial guidance before the opening bell, the implications were quickly digested by institutional investors. Pre-market trading showed Intel shares down significantly, setting the tone for what would become a day of panic selling.
- Market Open: When the opening bell rang, Intel stock gap-down opened sharply. The selling pressure was immediate and relentless. Within the first hour of trading, the stock had already shed a fifth of its value.
- The Mid-Day Acceleration: By midday, the "Intel contagion" had fully materialized. As algorithmic trading systems triggered sell orders based on the stock’s breach of key support levels, the decline accelerated. It became clear that this was not merely a reaction to poor earnings, but a fundamental reassessment of Intel’s position in the global chip market.
- The Sector-Wide Wipeout: As Intel’s decline deepened, the weakness spread to other semiconductor equities. NVIDIA, AMD, Broadcom, and TSMC all saw their valuations under heavy pressure. By the close of the trading session, the aggregate loss across the semiconductor sector had reached an estimated $1 trillion, according to data provided by Benzinga.
- The Close: When the market finally closed, Intel had cemented its position in the history books for all the wrong reasons. A 30% single-day loss stands as a testament to the magnitude of the market’s disappointment.
Supporting Data: By the Numbers
To understand the scale of this loss, one must look at the quantitative data behind the narrative.
- Market Cap Erosion: $150 billion is a sum that exceeds the total market capitalization of many S&P 500 companies. To lose that amount in seven hours of trading is rare, occurring typically only in extreme macroeconomic crises.
- CCPG Revenue Projections: The forecasted 20%+ drop in the Client Computing Group represents a significant contraction in Intel’s addressable market. This decline is attributed to a combination of weakening consumer demand for PCs, a saturated laptop market, and increasing competitive pressure from ARM-based alternatives and AMD’s Ryzen series.
- The Industry "Ripple Effect": The $1 trillion figure cited for the broader semiconductor industry underscores a market-wide "de-risking" event. Investors, spooked by Intel’s guidance, questioned whether the malaise in the PC sector would inevitably bleed into the high-growth segments of data center and AI-related chips.
Official Responses and Internal Sentiment
In the immediate aftermath of the stock’s collapse, Intel’s leadership has faced intense pressure to provide clarity. While official statements have been measured, the undercurrent of the messaging is one of acknowledgment regarding the severity of the situation.
Company spokespeople have emphasized that the decline in the CCPG is a reflection of broader macroeconomic headwinds, including high inflation and fluctuating interest rates, which have dampened consumer spending on hardware. Intel leadership maintains that their long-term strategic plan—which includes the construction of massive fabrication plants (fabs) in Ohio and Arizona—remains on track.
However, internal sentiment, as reported by sources close to the company, suggests a "bunker mentality." Employees are bracing for potential cost-cutting measures, and there is an palpable urgency among the executive team to demonstrate that the company can navigate the current turbulence without compromising its foundry ambitions. Intel has signaled that it will provide a more detailed roadmap in the coming weeks, intended to reassure stakeholders that the company’s transition to a foundry model remains a viable path to long-term profitability.
Implications: A New Reality for Intel and the Industry
The events of Friday carry profound implications that will likely dictate the narrative for the semiconductor sector for the remainder of the year and beyond.
1. The Crisis of Confidence
The most immediate implication is the loss of institutional trust. When a blue-chip company loses nearly a third of its value in a single day, the barrier to entry for new investors becomes significantly higher. Intel will now have to prove its worth through consistent, boring, and profitable quarters—a tall order given the volatility of the tech sector.
2. The AI Divide
The market’s reaction also highlights the widening gap between traditional chip manufacturers and AI-centric firms. While Intel is struggling with its legacy PC business, companies like NVIDIA continue to command premium valuations due to their dominance in AI hardware. This "AI Divide" suggests that the market is no longer willing to value all semiconductor firms equally; it is aggressively filtering for growth, and Intel is currently on the wrong side of that filter.
3. Geopolitical and Manufacturing Pressures
Intel’s reliance on its internal manufacturing capability (the IDM model) is now under the microscope. If the CCPG, which feeds those factories, is shrinking, the economic justification for massive domestic chip manufacturing becomes more difficult to defend. The U.S. government, which has invested heavily in the CHIPS Act to bolster domestic production, will be watching Intel’s recovery closely. A failing Intel could jeopardize the strategic goals of domestic chip independence.
4. A Shift in Industry Dynamics
The $1 trillion wipeout across the broader industry suggests that investors are bracing for a cyclical downturn in the semiconductor market. If the PC segment is contracting, the question arises: is the data center market next? The broader semiconductor sector will likely experience increased volatility as it attempts to decouple its performance from Intel’s specific struggles.
Conclusion: The Road Ahead
Friday’s events represent a "watershed moment" for the semiconductor industry. For Intel, the path forward is narrow and steep. The company must simultaneously stabilize its cash-generating PC division while accelerating its transition into a foundry service provider—a task that is notoriously capital-intensive and fraught with technical risk.
The $150 billion loss is more than just a number; it is a signal that the era of easy growth for legacy chipmakers has concluded. As the industry moves forward, the focus will shift from sheer scale to agility, efficiency, and a demonstrable ability to navigate a market that is increasingly demanding excellence in AI integration. Intel’s recovery will not be measured in days or weeks, but in the years it takes to rebuild the trust of the global financial community and prove that it remains a foundational pillar of the silicon age.
For now, however, the dust is still settling. The semiconductor sector remains in a state of high alert, and the ripple effects of Friday’s collapse will be felt in boardrooms and trading floors across the globe for the foreseeable future. The question remains: was this a temporary setback, or the beginning of a fundamental restructuring of the industry’s hierarchy? Only time, and the next few quarterly reports, will tell.