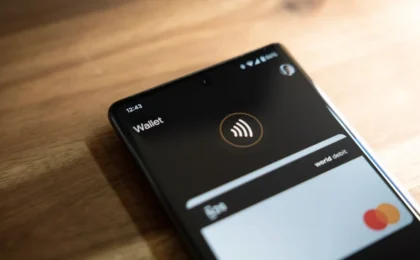

In a strategic move to position its artificial intelligence as a comprehensive "personal assistant" rather than just a generative text tool, Google has announced a significant integration between its Gemini chatbot and Google Wallet. This development marks a shift in how consumers interact with their financial data, moving away from static spreadsheets and manual banking app navigation toward a dynamic, conversational interface designed to provide personalized fiscal analysis.
However, the rollout comes at a time of intense scrutiny regarding the role of AI in personal finance. As industry titans like OpenAI and Meta move toward "agentic" models—AI that can execute transactions on behalf of users—Google has drawn a clear, conservative line in the sand: its new Gemini-Wallet integration is strictly for analysis, not for execution.
The Core Functionality: Analyzing, Not Acting
The integration allows users to grant Gemini "read-only" access to their Google Wallet data. By connecting these services, users can leverage Gemini’s large language model capabilities to parse complex financial information.
Unlike the burgeoning trend of autonomous "shopping agents" currently being tested by competitors, Google’s latest feature is designed to be an analytical engine. According to Google, users can ask the chatbot specific questions about their accounts, such as, "How much have I spent on subscriptions this month?" or "Why did my monthly utility bill increase?"
The value proposition here is one of accessibility. While an experienced user might be able to find these answers by exporting CSV files from their bank or scrolling through transaction history, Gemini aims to synthesize that data into plain language. More importantly, the system is designed to generate dynamic, visual aids. Users can request custom budgets for specific timeframes, which the AI then renders into charts tracking cash flow, asset allocation, and spending trends. With the holiday season approaching, Google is emphasizing the tool’s utility in creating seasonal budgets to help users stay on track during high-spending periods.
A Chronology of the AI Financial Shift
The integration of AI into the personal finance sector has accelerated rapidly over the last 18 months, representing a paradigm shift from traditional banking apps to AI-driven wealth management.
- Early 2026: AI development begins to pivot from creative writing and coding assistance toward "agentic" capabilities—systems capable of browsing the web and completing tasks.
- Mid-2026: The conversation around "AI Shopping Agents" heats up. Meta announces "Meta Muse," a chatbot designed to assist in product discovery and purchasing.
- October 2026: Controversy erupts as major service providers, including United Airlines, Delta, and Amazon, move to explicitly ban AI shopping agents from their platforms, citing concerns over unauthorized bookings and site stability.
- Late October 2026: OpenAI introduces "Dots," an agentic system that allows users to connect banking credentials to facilitate automated shopping.
- November 13, 2026: Google officially announces the Gemini-Google Wallet integration, distancing itself from the "transactional" AI trend by emphasizing a "read-only" security model.
Supporting Data and Technical Architecture
To facilitate this depth of insight, Google has entered a strategic partnership with Plaid, a leading fintech infrastructure company known for its secure API connections between financial institutions and third-party apps. While Google has remained tight-lipped regarding the granular details of the partnership, the inclusion of Plaid suggests that the integration will be able to pull data from a wide array of banking institutions, potentially extending the utility of the Gemini tool far beyond cards stored directly in a user’s Google Wallet.
Security and Privacy: The Opt-in Mandate
Given the sensitivity of banking data, Google has implemented a "security-first" framework. The system is strictly an opt-in experience, meaning no user data is exposed to Gemini unless the user explicitly grants permission through the settings menu.
Crucially, the architecture is designed with "guardrails." Gemini does not have the administrative clearance to:
- Initiate wire transfers or payments.
- Manage investment portfolios.
- Modify existing account settings.
- Execute purchases on external websites.
By limiting the AI to a "read-only" state, Google is attempting to mitigate the risks associated with "hallucinations"—the tendency of AI models to make errors or provide incorrect information. By keeping the AI away from the "transaction button," the company ensures that even if Gemini provides a faulty analysis, the user’s actual balance remains untouched.
Implications for the Future of Fintech
The launch of this feature poses several significant questions for the future of the digital economy and the relationship between users and their financial institutions.
The Conflict Between "Agents" and "Platforms"
The current friction between AI companies and service providers like Amazon and major airlines highlights a growing "Cold War" in the digital space. Companies want to maintain control over their user experience, pricing, and data. If an AI agent acts as a middleman, it strips the company of its ability to upsell products or manage inventory in real-time.
Google’s decision to focus on analysis rather than action may be a calculated attempt to avoid the "ban hammer" currently falling on OpenAI and Meta. By acting as a financial advisor rather than a purchasing proxy, Google remains an ally to the banking sector rather than a disruptor that creates security headaches.
The Changing Landscape of Personal Finance
For the average consumer, this technology represents the democratization of high-end financial planning. Previously, personalized budget analysis was the domain of human financial advisors or expensive, subscription-based accounting software. By embedding these tools into an AI chatbot, Google is lowering the barrier to entry for financial literacy.
However, there is a risk of over-reliance. As chatbots become more persuasive, users may be tempted to trust their financial health to an algorithm that does not fully understand the complexities of tax law, debt-to-income ratios, or long-term investment volatility. The "fun" factor of asking a bot about your spending habits could, in some cases, mask the underlying reality of poor financial management.
Official Responses and Industry Outlook
Google’s official statement frames the initiative as a way to enhance "personal intelligence." A spokesperson for the company stated: "Personal Intelligence in Gemini securely connects information from apps you already use to make your experience more personalized and helpful."
While the tech community has praised the ease of use, financial analysts are watching closely. The partnership with Plaid is seen as a signal that Google intends to scale this feature aggressively. Whether other banks will welcome this integration or attempt to restrict Google’s access remains to be seen. Major financial institutions often guard their data pipelines with extreme jealousy; if Google continues to expand its "read-only" ecosystem, it may eventually face the same pushback from the banking sector that airlines have leveled against AI booking agents.
Conclusion
The integration of Gemini with Google Wallet is a defining moment in the evolution of AI. It signals a move away from the "novelty" phase of generative AI and toward a "utility" phase, where the software is expected to handle real-world tasks.
By carefully choosing to remain an analytical assistant rather than an execution agent, Google has chosen the path of least resistance. It avoids the regulatory and security nightmares currently plaguing its competitors while still providing a service that many consumers will find genuinely useful. As the feature rolls out across mobile and web platforms, the success of this tool will likely depend on its accuracy. If the AI can provide reliable, actionable insights without the dreaded "hallucinations," it could become a staple of modern personal finance. If it fails to keep pace with the realities of banking data, it may serve as a warning of the limitations of AI in the high-stakes world of money management.